Iowa Small Business Financing
SBA Loans for Iowa Small Businesses
FSB helps Iowa business owners explore SBA-backed small business loans for working capital, equipment, real estate, business expansion, ownership changes, and eligible debt refinancing. You work with a local business lender who can help you understand the program, documentation, and financing structure that may fit your plans.
Working Capital
Support eligible operating expenses and short- or long-term business needs.
Equipment
Finance machinery, vehicles, tools and other eligible business equipment.
Real Estate
Purchase, build, improve or refinance eligible owner-occupied business property.
Business Growth
Fund eligible expansion, ownership changes and other qualified business purposes.
Compare SBA Small Business Loan Options
The right SBA loan depends on how you plan to use the funds, the size of the project and your business's financial profile. FSB can help you evaluate the options available for your financing request.
What Is an SBA Loan?
An SBA loan is business financing made by a participating lender and supported by a U.S. Small Business Administration guarantee. The SBA guarantee can help eligible small businesses access financing with program-specific terms and requirements.1
Flexible Business Financing
SBA 7(a) Loans
SBA's primary business loan program can provide up to $5 million for a range of eligible business needs.1
- Working capital
- Real estate acquisition, improvement or refinancing
- Machinery, equipment, furniture and supplies
- Eligible business debt refinancing
- Complete or partial changes of ownership
Major Fixed Assets
SBA 504 Loans
SBA 504 financing is designed for major fixed assets such as owner-occupied real estate and long-term equipment. The SBA-backed 504 loan portion can be up to $5.5 million.1
- Purchase or construction of land and buildings
- Renovation or improvement of eligible facilities
- Long-term machinery and equipment
- Long-term, fixed-rate financing on the CDC portion
- Structured with a Certified Development Company and private-sector lender
2026 SBA financing update: Effective July 4, 2026, eligible borrowers may combine 7(a) and 504 financing for up to $10 million in cumulative SBA-backed financing. Your lender can help determine whether a combined structure applies to your project.1
Why Work With FSB for an SBA or Small Business Loan?
Business financing is more than choosing a loan type. FSB's local team helps you understand the process, organize your financing request and stay connected from the first conversation through closing.
Local Business Lenders
Work directly with business bankers who serve Eastern Iowa companies and understand the local market.
Financing Built Around the Project
We look at how the funds will be used and help identify an SBA or conventional business loan structure that may fit.
Guidance Through Documentation
Your lender can help explain the financial information and supporting documents needed for the application and underwriting process.
A Relationship Beyond Closing
Continue working with a local FSB team for business banking, treasury management and future financing needs.
Eastern Iowa Business Lending
Local SBA & Small Business Lenders in Eastern Iowa
FSB works with business owners throughout Cedar Rapids, Marion, Hiawatha, Tiffin, Iowa City and surrounding Eastern Iowa communities. Our local lenders can help you compare SBA financing with other business loan options and understand what comes next in the process.
Looking for a small business loan lender near your business? Start with an FSB lender or visit a nearby branch to begin the conversation.
Find a Business LenderExplore FSB Locations
How to Apply for an SBA Small Business Loan
The exact process depends on the SBA program and your financing request, but most borrowers move through the same four stages with their lender.
1
Talk With a Lender
Discuss your business, financing goal, use of funds and desired timeline.
2
Submit Financial Information
Provide the application and requested business and personal financial documents.
3
Underwriting & SBA Review
The lender reviews repayment ability, eligibility and the SBA requirements that apply.
4
Closing & Funding
Complete final requirements, sign loan documents and receive funds according to the approved structure.
Eligible Uses Vary by Program
What Can an SBA Small Business Loan Be Used For?
SBA loans can support several business needs, but eligible uses depend on the specific program and transaction. A lender can help you match the use of funds to the appropriate SBA loan.
- Working capital: Support eligible payroll, operating expenses and short- or long-term business needs.
- Equipment purchases: Finance eligible machinery, vehicles, tools, furniture and fixtures.
- Commercial real estate: Acquire, build, improve or refinance eligible owner-occupied business property.
- Business expansion: Add capacity, locations or other eligible growth investments.
- Ownership changes: Finance an eligible complete or partial business acquisition through the 7(a) program.
- Debt refinancing: Refinance eligible business debt when SBA program requirements are met.
SBA 504 financing is focused on major fixed assets and generally cannot be used for working capital or inventory. SBA 7(a) financing can support a broader range of eligible business purposes.
“We opened our doors in 2006, and our business has grown exponentially. FSB helped us get started and has supported us every step along the way.”
Justin & Sara W.
Frequently Asked Questions About SBA Loans
Get clear answers to common questions about SBA loans, eligibility, down payments, timelines and financing options for Iowa small businesses.
What is an SBA loan and how does it work?
An SBA loan is business financing made by a participating lender and supported by a U.S. Small Business Administration guarantee. The lender evaluates and underwrites the request while SBA program requirements also apply. For 504 financing, a Certified Development Company works with a private-sector lender to structure the project.
What qualifies you for an SBA loan?
Eligibility varies by program, but SBA generally requires an eligible business to be operating for profit, located in the United States, small under SBA size standards and able to demonstrate a reasonable ability to repay. The lender also evaluates creditworthiness, cash flow, the use of funds and other underwriting requirements.
What is the easiest SBA loan to get?
There is not one SBA loan that is automatically the easiest to qualify for. Approval depends on the program, the use of funds, business history, creditworthiness, repayment ability and the completeness of the application. SBA 7(a) loans can support a broad range of business needs, while 504 financing is designed primarily for major fixed assets.
What down payment is required for an SBA loan?
There is no single down payment requirement for every SBA loan. A typical 504 project includes a borrower contribution of at least 10 percent, although a higher contribution may apply in some situations. Equity requirements for 7(a) loans depend on the transaction, SBA requirements and lender underwriting.
How long does it take to get approved for an SBA loan?
There is no fixed approval timeline for every SBA loan. Timing depends on the loan program, the complexity of the transaction, the documentation provided, underwriting and any third-party requirements such as appraisals or environmental reviews. A complete application can help reduce avoidable delays.
What is the difference between an SBA 7(a) loan and a 504 loan?
SBA 7(a) is the SBA's primary business loan program and can provide up to $5 million for eligible uses including working capital, real estate, equipment, debt refinancing and ownership changes. SBA 504 financing is designed for major fixed assets such as owner-occupied real estate and long-term equipment, with the SBA-backed 504 loan portion available up to $5.5 million.
Can SBA 7(a) and 504 loans be combined?
Yes. Effective July 4, 2026, eligible borrowers may combine 7(a) and 504 financing for up to $10 million in cumulative SBA-backed financing. Whether that structure fits a project depends on SBA eligibility, the use of funds and lender underwriting.
How do SBA Microloans work?
SBA Microloans provide up to $50,000 and are administered through specially designated nonprofit intermediary lenders rather than through the standard bank 7(a) or 504 process. If your business needs a smaller loan or startup financing, an FSB business lender can discuss available financing options and help you identify the next step.
Choose FSB As Your Iowa SBA Lender
With in-house decision-making, flexible financing options, and local lending experts, FSB makes securing the right funding in Eastern Iowa easy, so you can focus on growing your business.
Ready to Apply For a Small Business Loan?
Complete FSB’s simple business inquiry form below, and a business lender will reach out for additional information.1
Simplify Your Banking Experience
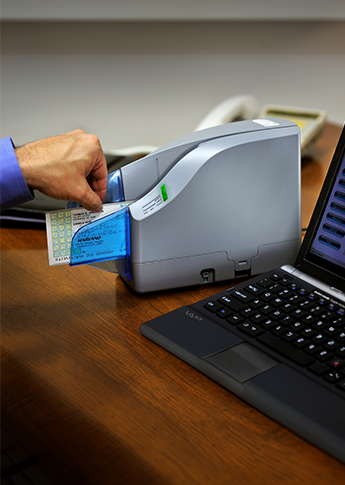
Deposit checks without leaving your office with FSB's Remote Deposit.