How to Teach Kids About Money in a Digital World
By Farmers State Bank | Updated: September 30, 2026 • 9 min read

 1240 8th Avenue Marion IA 52302319-377-4891
By Farmers State Bank | Updated: September 30, 2026 • 9 min read
In today’s world, children are growing up in an environment where spending money is often as simple as tapping a screen. From in-app purchases and online shopping to social media influencers promoting the latest trends, children face financial decisions earlier than ever before. While technology creates new challenges, it also offers valuable opportunities to teach financial literacy.
By introducing financial lessons early, parents can help their children develop healthy money habits that will aid them throughout their lives. Understanding the challenges children face online and incorporating simple money lessons into everyday life can help set them up for long-term financial success.
Financial literacy is not simply about dollars and cents. It is about helping children understand choices, consequences, and long-term planning. The goal is not for a young child to understand every financial product. It is to give them age-appropriate practice making decisions with money.
Today’s children are growing up with digital wallets, debit cards, online marketplaces, and mobile payment options that have become a normal part of everyday life. Because digital transactions are less visible, children may struggle to understand the concept of money leaving their possession. Swiping or tapping a card does not feel the same as handing over cash.
That disconnect can make it harder for children to understand the value of money and develop mindful spending habits. One way to make digital money more concrete is to show your child an account balance before and after a purchase. Reviewing the receipt or transaction history together helps connect the tap of a card with the money that actually left the account.
Children begin forming attitudes about money at an early age. Their observations of family spending habits, advertising messages, and peer influence all play a role in how they view money. Without guidance, children may develop habits such as impulsive spending that become difficult to change later in life.
You do not need to include children in every financial decision your household makes. Simple conversations about why you are waiting for a sale, comparing two prices, saving before a purchase, or deciding not to buy something can give them useful context.
Financial literacy plays a significant role in long-term financial success. Adults who understand budgeting, saving, and responsible spending are better equipped to work toward their goals. By teaching children about money early, parents can help them build confidence and decision-making skills that extend beyond finances.
Technology has transformed how we earn, spend, and save money. While this offers convenience, it also creates challenges that many parents did not face growing up.
Many popular games use virtual currencies that can blur the line between real and digital money. Features like limited-time offers and reward systems can encourage impulsive buying. Parents should discuss how virtual spending works and teach children to pause and think before making a purchase.
Try this: Before approving an in-app purchase, translate the virtual currency back into dollars with your child. Ask whether they would still buy the item if they had to hand over the same amount in cash.
Children and teens are constantly exposed to influencers highlighting new products, trends, and lifestyles. These messages can create unrealistic expectations and encourage unnecessary spending. Help your children understand that social media often presents a carefully selected version of reality rather than the full picture.
You can also teach them to identify sponsored posts, product placements, affiliate links, and other forms of advertising. Knowing when someone is being paid to promote a product can help children evaluate the message more critically.
Online retailers have made buying easier than ever. The convenience of instant purchases can make it difficult for children to learn patience and delayed gratification. Teaching children to wait before making non-essential purchases helps them develop more thoughtful financial decision-making skills.
A simple waiting period can help. For a smaller purchase, wait until the next day. For a larger purchase, consider waiting a week or longer. If they still want the item after the waiting period, talk through the cost and what they may need to give up or delay to buy it.
Saved payment information, subscriptions, and one-click checkout can make spending feel almost automatic. Explain that convenience does not make a purchase free. Older children and teens should understand recurring charges, free trials that turn into paid subscriptions, and why it is important to review transactions regularly.
While the digital world presents unique financial challenges, it also creates opportunities for parents to teach valuable money management skills. The key is to turn everyday experiences into learning moments that help children develop confidence and responsibility when making financial decisions.
Money lessons become more useful when they match what your child can understand and the financial decisions they are beginning to make. You can build on the same basic ideas as they get older.
Young children benefit from seeing and handling money. Focus on simple concepts such as earning, spending, saving, and the difference between needs and wants.
As children begin making more independent choices, give them opportunities to manage a limited amount of money. An allowance, gift money, or money earned from small jobs can help them practice.
Teenagers can begin learning the financial skills they will use when they start working, driving, going to college, or managing more of their own expenses.
For an easy budgeting framework, older teens can also learn how the 50/30/20 budgeting rule divides money between needs, wants, and savings.
Teaching children about money does not require formal lessons. Many of the most effective opportunities happen during everyday life.
One of the most important money lessons for children is knowing the difference between a need and a want. Needs include things like food, water, shelter, and clothing. Wants are items that may be enjoyable but are not essential. Helping children understand the difference encourages thoughtful spending habits and better financial choices.
You can practice this at the grocery store, while looking at online purchases, or when your child asks for something new. The goal is not to suggest that wants are bad. It is to help them understand that needs usually come first when money is limited.
Saving becomes more meaningful when children have a specific goal in mind. Goals provide motivation and reinforce the value of patience. Watching savings grow over time helps children understand how consistent habits lead to meaningful rewards.
Parents can help by breaking larger goals into smaller milestones. For example, if a child wants to buy a new gaming system, tracking progress toward that goal can make saving more engaging and reinforce the value of delayed gratification.
Children need opportunities to practice. If every financial decision is made for them, they do not get to experience tradeoffs. Giving a child control over a small, age-appropriate amount of money lets them decide whether to spend now or save for later.
Small mistakes can become useful lessons. If they spend their money and later wish they had saved it for something else, talk about what they might do differently next time instead of immediately replacing the money.
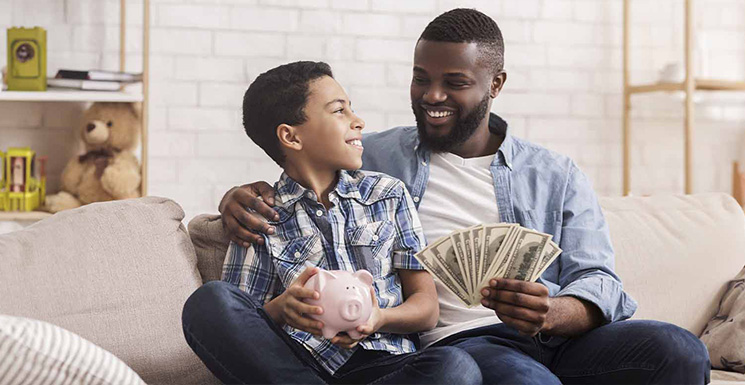
If your child uses a debit card, youth account, or another digital payment method, review the activity together. Show them how purchases reduce the available balance and how deposits increase it. This helps connect digital transactions with real money.
FSB's Banking for Kids resources and youth accounts can also help families introduce saving and banking through real-world experience.
Children learn from observation. It is important to model responsible spending, budgeting, and saving habits in your own life. Share age-appropriate financial decisions and explain the reasoning behind them.
When children see positive financial behavior consistently, they are more likely to adopt those habits themselves. You might explain why you are saving for a purchase, comparing prices, avoiding an impulse buy, or setting aside money before spending on something optional.
You do not need a complicated lesson plan. A short routine repeated regularly can help money conversations become a normal part of family life.
Help your child choose something specific to save for and write down the amount they need.
When your child receives money, decide how much will be available to spend now and how much will go toward savings. Some families also include a giving category.
Use a receipt, bank transaction, or online purchase to show what was spent, what remains, and whether the purchase matched the plan.
Review the savings goal weekly or monthly. Recognize progress and adjust the plan if the goal or your child's priorities change.
Raising financially responsible kids in a digital world requires more than teaching them how to save money. It means helping them understand how spending decisions, online influences, and financial habits shape their long-term future.
By starting early, providing practical experiences, and modeling healthy money behavior, parents can equip their children with the financial literacy skills they need to manage money in a digital economy.
The habits children develop today can influence the decisions they make for years to come. When children learn to manage money responsibly early on, they build confidence and greater independence as they work toward their future goals.
Continue building your own knowledge alongside your child with more resources from FSB's Financial Wellness Center.
Money lessons do not need to be complicated. These answers can help you decide where to start and which skills to introduce as your child gets older.
You can start with simple concepts as soon as your child begins asking about buying things. Younger children can practice identifying needs and wants, counting money, and saving for a small goal. As they get older, you can add budgeting, banking, digital payments, and credit.
Make digital transactions visible. Show your child the account balance before and after a purchase, review a receipt together, and explain that tapping a card or phone still moves real money out of an account. For younger children, using cash for some purchases can make the exchange easier to understand.
An allowance can be a useful teaching tool when the rules are clear. Some families connect allowance to chores, while others use it to give children regular practice with saving and spending. The amount matters less than giving your child a chance to make choices, track money, and learn from small mistakes.
Teens should understand how to build a basic budget, read an account balance and transaction history, use a debit card, save for short-term goals, recognize the difference between debit and credit, and understand why bills and loan payments need to be paid on time.
Start with one specific goal. Help your child name what they want to save for, determine the cost, decide how much they can set aside each week or month, and track progress. A visible goal makes saving easier to understand than simply telling a child to save more.
Help your child practice saving, spending, and banking with age-appropriate resources and youth account options from FSB.
Explore Banking for Kids
Discover simple ways to save this summer without missing out on fun.
Stay ahead of inflation with tips to adjust your budget and manage debt.
Explore the best ways to fund your child's college education.